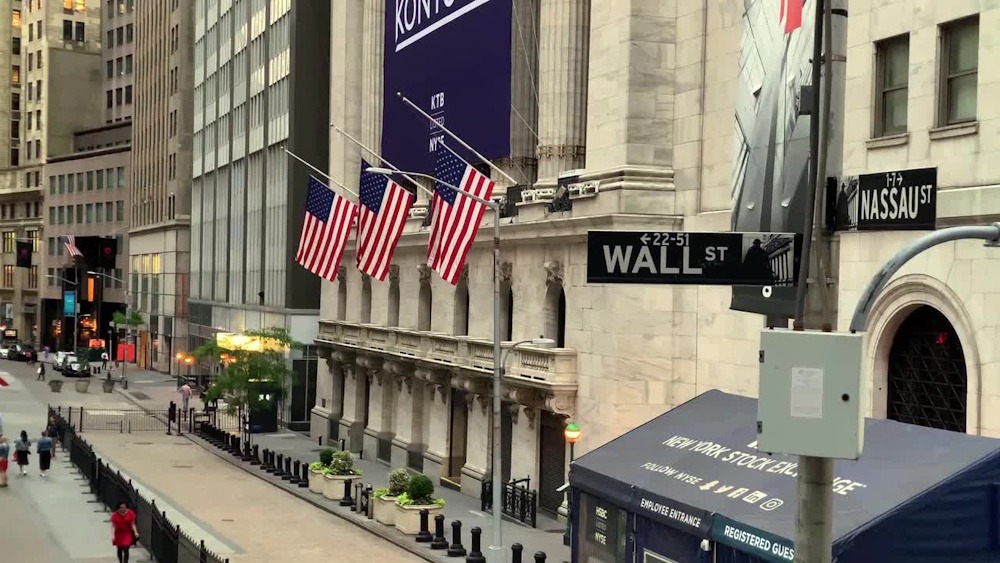
Nasdaq futures displayed slight variations on Monday as market participants braced for a pivotal week marked by bank earnings and inflation data, alongside the closure of U.S. bond markets. Futures for the Dow Jones Industrial Average and S&P 500 registered an increase of 0.1% each, while Nasdaq 100 futures experienced a decrease of 0.1%. Earnings season commences in earnest tomorrow, as several prominent financial institutions-JPMorgan Chase, Goldman Sachs, Wells Fargo, and Citigroup-are set to disclose their results. Additionally, Johnson & Johnson and UnitedHealth Group are scheduled to report their earnings prior to the market opening. Investors will closely monitor the Bureau of Labour Statistics’ September Consumer Price Index reading on Wednesday, along with the wholesale Producer Price Index data on Thursday.
Stocks experienced a significant uptick on Friday, leading to weekly gains for major indexes, as technology shares rebounded from the sell-off witnessed in the previous session. For the week, the benchmark S&P 500, blue-chip Dow, and tech-focused Nasdaq Composite recorded respective increases of 1.2%, 0.9%, and 0.6%. It represented the Nasdaq’s fourth consecutive weekly gain. While U.S. stock markets remain operational today in observance of Columbus Day, which is recognised in certain regions as Indigenous Peoples’ Day, bond markets are closed. The 10-year Treasury yield, a critical benchmark for various interest rates, closed around 5.24% on Friday, just two days after it briefly reached nearly 5.37%, marking its highest level in over 24 years.
Oil prices saw a slight uptick on Monday as investors weighed a range of developments. Saudi Arabia has reported the interception of missiles and drones overnight, in the wake of lethal attacks at the Riyadh airport, where operations remain suspended. Additionally, President Donald Trump stated yesterday that Russia and Ukraine had reached an agreement on a “energy ceasefire.” U.S. benchmark West Texas Intermediate crude futures have recently risen by 1% to $92.70 a barrel, while front-month Brent crude futures, the international benchmark, have increased by 0.9% to $105.65. In corporate news, Amazon shares, which led the Magnificent Seven mega-cap tech stocks with a more than 3% advance Friday, ticked higher before the bell following a report that it is in discussions to acquire software firm Decart for approximately $7 billion. The Roundhill Magnificent Seven ETF increased by 0.4% after experiencing a 1% rise on Friday.
Roundhill’s Memory ETF and the broader iShares Semiconductor ETF saw declines of approximately 2% and 1%, respectively, during premarket trading. Shares of T-Mobile US, AT&T, and Verizon Communications saw a slight recovery after a drop ranging from 8.5% to 13% on Friday, positioning them as the three largest decliners within the S&P 500. This movement followed the announcement by SpaceX, under the leadership of Elon Musk, regarding its agreement to acquire a nationwide low-band spectrum licence portfolio. SpaceX, which experienced an increase of more than 1% in the previous session, observed an additional rise of 0.5% ahead of the opening bell on Monday. Bitcoin was trading around 83,400, experiencing a minor decline over the past 24 hours. The U.S. dollar index, which tracks the value of the greenback against a basket of foreign currencies, rose by 0.2% to 102.38. Gold futures experienced a decline of 0.4%, settling at $4,200 per ounce.