Nasdaq futures indicated a predominantly positive trajectory on Thursday, disregarding the upward movement in Treasury yields and oil prices, as the trading for the fourth quarter and October was poised to commence. In recent trading, futures for the Nasdaq 100 and S&P 500 exhibited increases of 0.5% and 0.2%, respectively. Futures for the Dow Jones Industrial Average exhibited a slight decline. Yesterday, the tech-focused Nasdaq Composite advanced on the final trading session of the third quarter, buoyed by the Federal Reserve’s preferred inflation gauge, which came in lighter than anticipated. In contrast, the blue-chip Dow and benchmark S&P 500 experienced a pullback. The Dow and S&P 500 concluded September on a downward trajectory, while the Nasdaq experienced an uptick; for the quarter, the Dow registered a decline, contrasting with the gains observed in both the Nasdaq and S&P 500.
With global bond yields surging, the 10-year Treasury yield, which serves as a benchmark for a wide range of interest rates, including those for mortgages, corporate bonds, and other loans, reached a new 24-year high of nearly 5.35% early Thursday. The yield recently stood at 5.31%, reflecting an increase of nearly two basis points from Wednesday’s close. Oil prices experienced an uptick on Thursday following a report indicating that Chinese refiners had halted fuel exports for October to focus on meeting domestic demand. U.S. benchmark West Texas Intermediate crude futures experienced an increase of 2%, reaching $92.25 per barrel in recent trading. Meanwhile, front-month Brent crude futures, serving as the international benchmark, rose by 2.7% to $100.65.
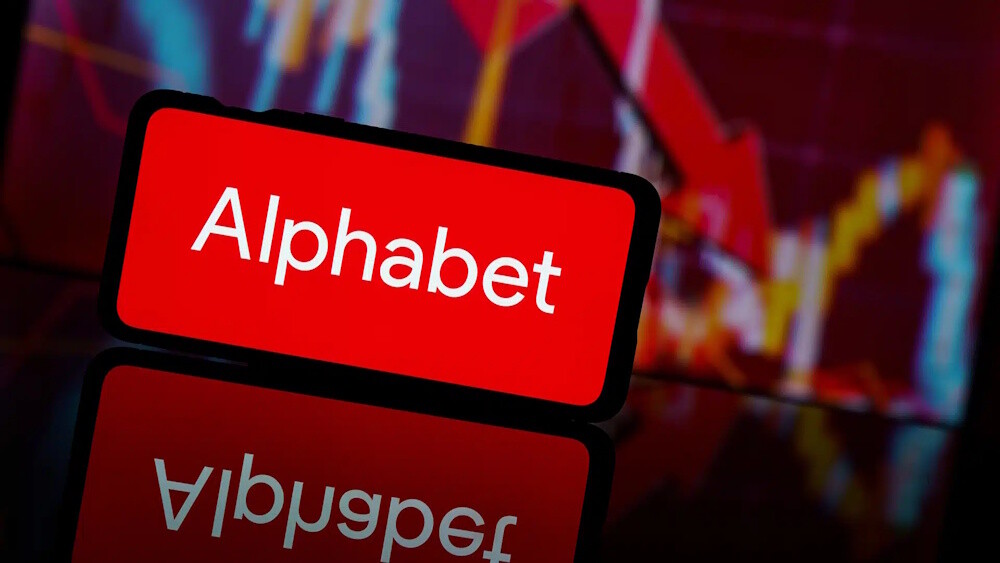
Shares of the Magnificent Seven mega-cap tech firm Alphabet rose 2.5% before the bell following the unveiling of Gemini 4 Argon, its most advanced AI model. Meta Platforms shares ticked higher a day after the Facebook parent was the only member of the septet to close lower. The Roundhill Magnificent Seven ETF pointed up nearly 1%. Memory stocks and other AI-related companies experienced an uptick prior to the market opening. Roundhill’s Memory ETF and the broader iShares Semiconductor ETF experienced an increase of approximately 1.5% each, as digital storage companies Seagate Technology, Sandisk, and Western Digital all saw gains.
In the aftermath of earnings announcements, Accenture shares experienced a significant increase of 15%, whereas Micron Technology saw a modest decline of less than 1%, despite reporting results that exceeded expectations and providing an optimistic forecast. Nike was slated to report results after markets close today. Bitcoin traded at approximately $83,600, exhibiting minimal variation over the preceding 24 hours. The U.S. dollar index, which monitors the value of the greenback relative to a selection of foreign currencies, increased by 0.5% to 101.98. Gold futures declined by 0.1%, settling at $4,180 per ounce.