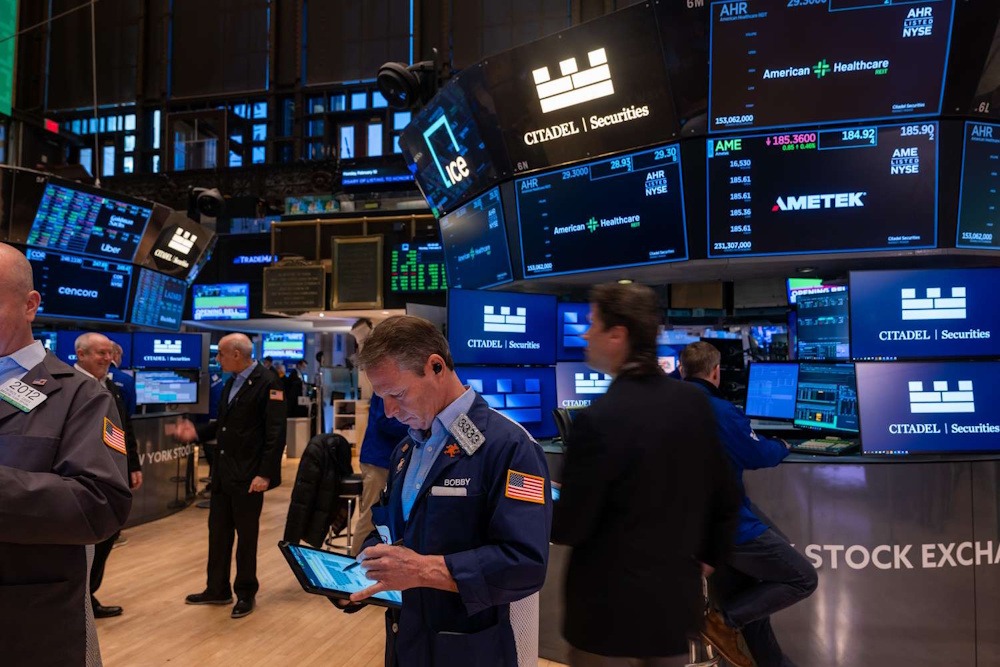
Nasdaq futures experienced a significant decline on Thursday, while S&P 500 futures also retreated, as stocks associated with artificial intelligence faced a sell-off due to apprehensions regarding the debt burdens necessary for developing AI infrastructure. In recent trading, futures for the Nasdaq 100 and S&P 500 indicated declines of 1.2% and 0.3%, respectively. Futures for the Dow Jones Industrial Average exhibited an increase of 0.2%. Yesterday, the tech-focused Nasdaq Composite and benchmark S&P 500 experienced their most significant declines since July, falling by 1.9% and 1.1% respectively. This downturn followed the Consumer Price Index reading for September, which exceeded economists’ forecasts, thereby increasing the likelihood of an interest rate hike by the Federal Reserve later this month. The blue-chip Dow experienced a decline of 0.1%.
CoreWeave stock sank more than 15% to lead Nasdaq 100 decliners Wednesday on concerns about the Nvidia-backed firm’s debt to fund the buildout of AI data centers. Worries continued today, with shares down a further 5% before the bell. Other stocks associated with AI experienced a significant decline ahead of the market opening on Thursday. SK Hynix, Micron Technology, Sandisk, Seagate Technology, and Western Digital continue to exert pressure on Roundhill’s Memory ETF, which experienced a decline of nearly 7% after a 5% decrease the previous day. The broader iShares Semiconductor ETF pointed down about 3% after falling 4.5%. Nvidia and Meta Platforms, which led the Magnificent Seven mega-cap tech stocks lower Wednesday with pullbacks of more than 3%, were down a further 1.5% and 1%, respectively, and the Roundhill Magnificent Seven ETF, which tracks the group, declined more than 1% premarket.
Apple, which yesterday joined Nvidia as the only companies ever to close with a market capitalisation above $5 trillion, rose less than 1%. Following the CPI reading that exceeded expectations yesterday, market observers are set to receive another inflation indicator at 8:30 a.m. today, with the release of the wholesale Producer Price Index data for September. Economists anticipate a month-over-month increase in wholesale prices of 0.6% and a year-over-year rise of 5.5%, compared to the previous figures of 0.4% and 5.4% in August. Additionally, data on September retail sales and weekly jobless claims is scheduled for release this morning. The 10-year Treasury yield recently stood at 5.08%, reflecting a decline of over 10 basis points from Wednesday’s close. The yield had soared to 5.33% following the CPI data released yesterday, only to reverse course as the tech-driven stock selloff prompted investors to seek safer assets.
Oil prices exhibited a mixed performance on Thursday as investors assessed the latest developments in the Middle East. This included a Reuters report indicating that the U.S. was contemplating the easing of sanctions on “shadow fleet” vessels from nations such as Russia, Iran, and Venezuela that are involved in the transportation of crude and petroleum products. U.S. benchmark West Texas Intermediate crude futures increased by 0.1% to $95.25 a barrel in recent trading, whereas front-month Brent crude futures, the international benchmark, decreased by 1.3% to $104.65. Bitcoin was trading around 80,900, down from overnight highs near 81,900. The U.S. dollar index, which monitors the value of the greenback relative to a selection of foreign currencies, experienced a decline of 0.5%, settling at 102.02. Gold futures increased by 1.7%, reaching a price of $4,175 per ounce.