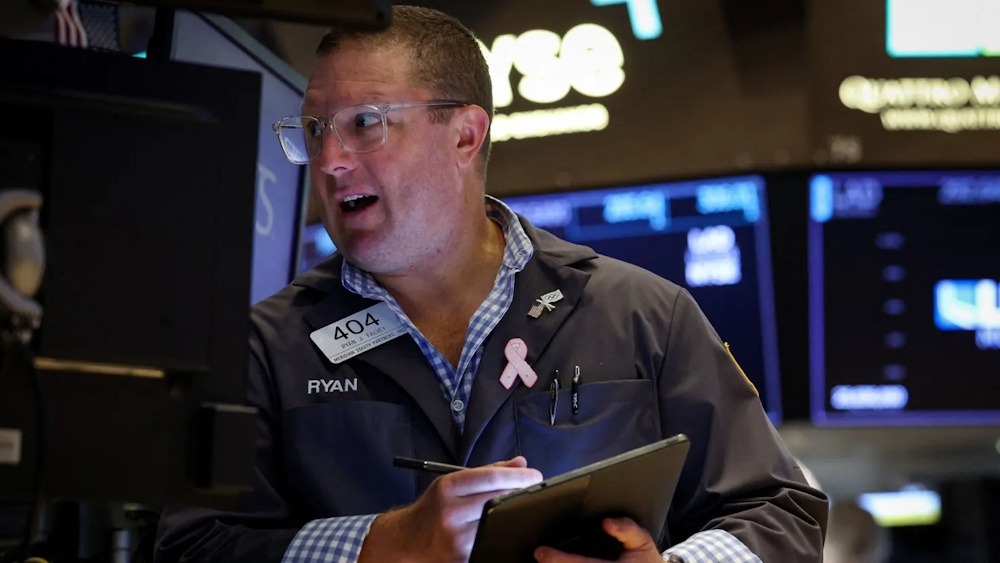
Nasdaq futures indicated a mixed opening on Friday, following a positive session for the major U.S. equity indexes. The Nasdaq Composite and S&P 500 are set to conclude the week on a lower note. In recent trading, the Dow Jones Industrial Average futures increased by 0.3%, while the S&P 500 futures saw a rise of 0.1%. Nasdaq 100 futures indicated a decline of 0.2%. As Friday approached, the tech-centric Nasdaq Composite and the benchmark S&P 500 experienced declines of 2.4% and 0.9% for the week, respectively, with the Nasdaq on track to end its four-week winning streak. The blue-chip Dow experienced an increase of 1%. Yesterday, U.S. indexes experienced an upward trajectory, with the Dow leading the charge, advancing by 1.1%, equivalent to 550 points, as investors shifted their focus away from technology stocks. Amid mounting pressure on the Federal Reserve to address inflation, following unexpectedly high Consumer Price Index and Producer Price Index figures in recent days, Chair Kevin Warsh, in remarks delivered at an International Monetary Fund meeting in Bangkok, refrained from indicating whether the central bank would maintain interest rates or opt for an increase at its upcoming policy meeting later this month or in early December.“It’s a new chapter at the Fed, and we’re not in that business anymore,” Warsh stated.
In light of Warsh’s remarks, traders currently assign a 15% probability to the Fed increasing rates at its late-October meeting, a decrease from the 28% observed yesterday, as per CME FedWatch. There remains an 89% probability of a rate increase at the December meeting, consistent with yesterday’s assessment. The 10-year Treasury yield was approximately 5.10% in recent trading, reflecting an increase of two basis points from Thursday’s close. The yield had soared to 5.33% following Wednesday’s CPI data, only to reverse course as the tech-driven stock selloff prompted investors to seek safer assets. In corporate news, CoreWeave shares were under pressure for the second time in three days Friday, falling more than 4% before the bell. On Wednesday, shares experienced a decline exceeding 15% due to apprehensions regarding the debt of the Nvidia-backed firm. However, they managed to reverse early losses yesterday, ultimately closing with a 6% increase.
Other stocks associated with the AI sector experienced declines before the market opened, following a significant pullback on Thursday. Roundhill’s Memory ETF experienced a decline of 14% in the initial four sessions of the week, with an additional downward movement of approximately 1.5%. This further decrease was influenced by the performance of key components such as Western Digital, Sandisk, Micron Technology, and Seagate Technology. The broader iShares Semiconductor ETF was down less than 1% premarket after having fallen 8% this week through Thursday. However, Roundhill Magnificent Seven ETF, which tracks the Magnificent Seven mega-cap tech stocks, was approximately 1% higher before the market opened. Tesla shares powered the group with a 5% premarket rise after it unveiled its Roadster all-electric sports car last nite.
Nvidia, the world’s most valuable public company, rebounded modestly from a nearly 2% loss yesterday to rise about 0.5%. Oil prices experienced a modest decline as traders assessed the geopolitical risks in the Middle East in relation to initiatives aimed at boosting supply. U.S. benchmark West Texas Intermediate crude futures declined by 0.4% to $97.55 a barrel in recent trading, whereas front-month Brent crude futures, the international benchmark, decreased by 0.2% to $105.75. Bitcoin was trading around 81,900, down slightly over the past 24 hours. The U.S. dollar index, which monitors the value of the greenback relative to a selection of foreign currencies, decreased by 0.9% to 101.63. Gold futures increased by 0.7% to $4,200 per ounce.